ClermontFerrand, France – Global sellin volumes for passenger and lighttruck tires remained stable yearoveryear across JanuarySeptember 2026, according to market data shared by Michelin during its Q3 2026 business update. A 1percent decline in originalequipment (OE) tire sales was largely offset by a 1percent rise in replacementtire demand worldwide.
Regional market dynamics varied considerably amid shifting automotive demand, trade measures and consumer purchasing power.
In Europe, OE tire demand held flat yearonyear. Growth was underpinned by accelerating electricvehicle uptake and public incentive schemes in selected markets. Nevertheless, rising imports of finished vehicles from outside the region continued to cap local automotive production capacity, limiting upside for local OE tire business.
Replacementtire sellin volumes in Europe fell 1 percent for the first nine months, with a sharper drop recorded in Q3. The contraction was mainly triggered by EU antidumping policies targeting Chineseorigin tires, which reduced inflows of lowcost imported tires. For years the European aftermarket relied heavily on costcompetitive import tires. New trade barriers have created supply gaps for valueoriented products and opened sharegain opportunities for local and premium tire suppliers, alongside shortterm volatility in channel inventories and procurement costs. The competitive landscape for lowpriced replacement tires in Europe is undergoing fundamental change.
The Americas market posted moderate pressure across both segments. OE volumes slipped 1 percent while replacement sellin declined 3 percent yeartodate. Higher vehicle prices driven by customs tariffs, elevated interest rates and increased fuel costs eroded household purchasing power.
An important market signal emerged: while distributorlevel sellin figures softened, endconsumer sellout demand remained resilient. Market segmentation has intensified, with midtier brands facing mounting pressure. Both premium and economy tire segments maintained solid performance, squeezing room for midrange products. This polarisation trend is expected to persist in the region.
China presented a clear divergence between OE and replacement performance. OE tire volumes dropped 7 percent yearoveryear, resulting from proactive inventory corrections by local automakers and fading policy incentives for newcar purchases. Even with softer domestic vehicle consumption, exports of Chinese hybrid and batteryelectric vehicles hit record highs.
China’s replacementtire market grew 6 percent in the JanuarySeptember period. The expansion was fuelled by a strong replacement cycle from large numbers of vehicles sold in previous years. During Q3, previously inflated lowcost tire channel inventories returned to more normal levels.
This split illustrates a core feature of China’s tire industry: the OE tire business is tightly tied to newcar output with limited upside, while the replacement aftermarket acts as a stable revenue base for domestic tire manufacturers. Chinese tire producers are readjusting their strategies. Many follow domestic automakers into overseas markets to secure offshore OE opportunities, while at home they invest deeper in aftermarket distribution and lowertier city markets. Inventory swings for lowcost tires also directly affect operating rates and order books of smallandmidsized tire factories.
Globally, the passengertire industry has entered a lowgrowth era. Past volumedriven expansion is giving way to valueoriented structural opportunities. The replacement aftermarket keeps gaining weight, whereas OE tire performance fluctuates alongside automotive capacity shifts and crossborder trade policies.
Trade barriers have become a major factor reshaping global tire flows. Anti-dumping duties and customs tariffs are rewriting traditional supply patterns for low-cost cross-border tire shipments. Tire exporters are forced to prioritise localised overseas manufacturing capacity and develop newmarket channels.
Market polarisation is a worldwide phenomenon. Premium and economy tire segments hold steady across Europe, the Americas and China, while midtier players face fiercer competition. Brand positioning and channel capability carry greater weight than pure price competition.
For Chinese tire manufacturers, two strategic paths stand out: capture aftermarket cycle benefits to consolidate the domestic replacement base, and ride the boom of Chinese new-energy-vehicle exports to tap into overseas originalequipment business. These will represent key growth vectors for the coming years.
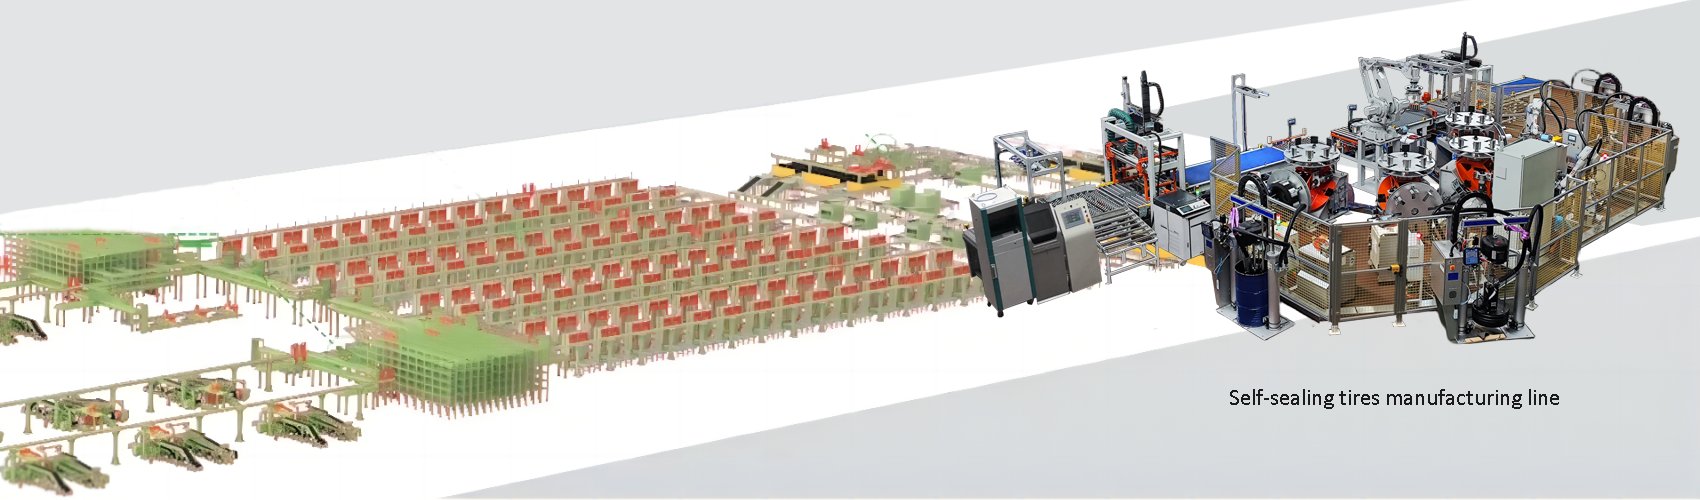
DLFTECH is a professional equipment marketing & service company built by a senior R&D and marketing team in the tire & conveyor belt equipment industry. Benefiting from the rapid follow up of the international rubber industry's process re-engineering and the demand for industrial intelligence, DLFTECH, the best of the best, has rapidly developed into a new star in the international rubber machinery industry.
If any tire or conveyor belt industry customers need such as tire bead winding line, tire mold laser cleaning system, hydraulic curing press for PCR/TBR, etc., please feel free to contact info@delphygroup.com.